

Hyperscaler and data-center investment, negligible through 2022, is now tracking toward $1.5 trillion annually by 2030. At that level, it will surpass, in real terms, the residential construction boom of 2005-06, the 1990s fiber build peak year, and the 1882 railroad peak combined. And it has reached funding escape velocity, with external debt and equity soon financing the majority of the buildout, with that share approaching 90% by 2030. AI infrastructure cycle is dependent on capital markets in a way that no prior technology cycle ever was.
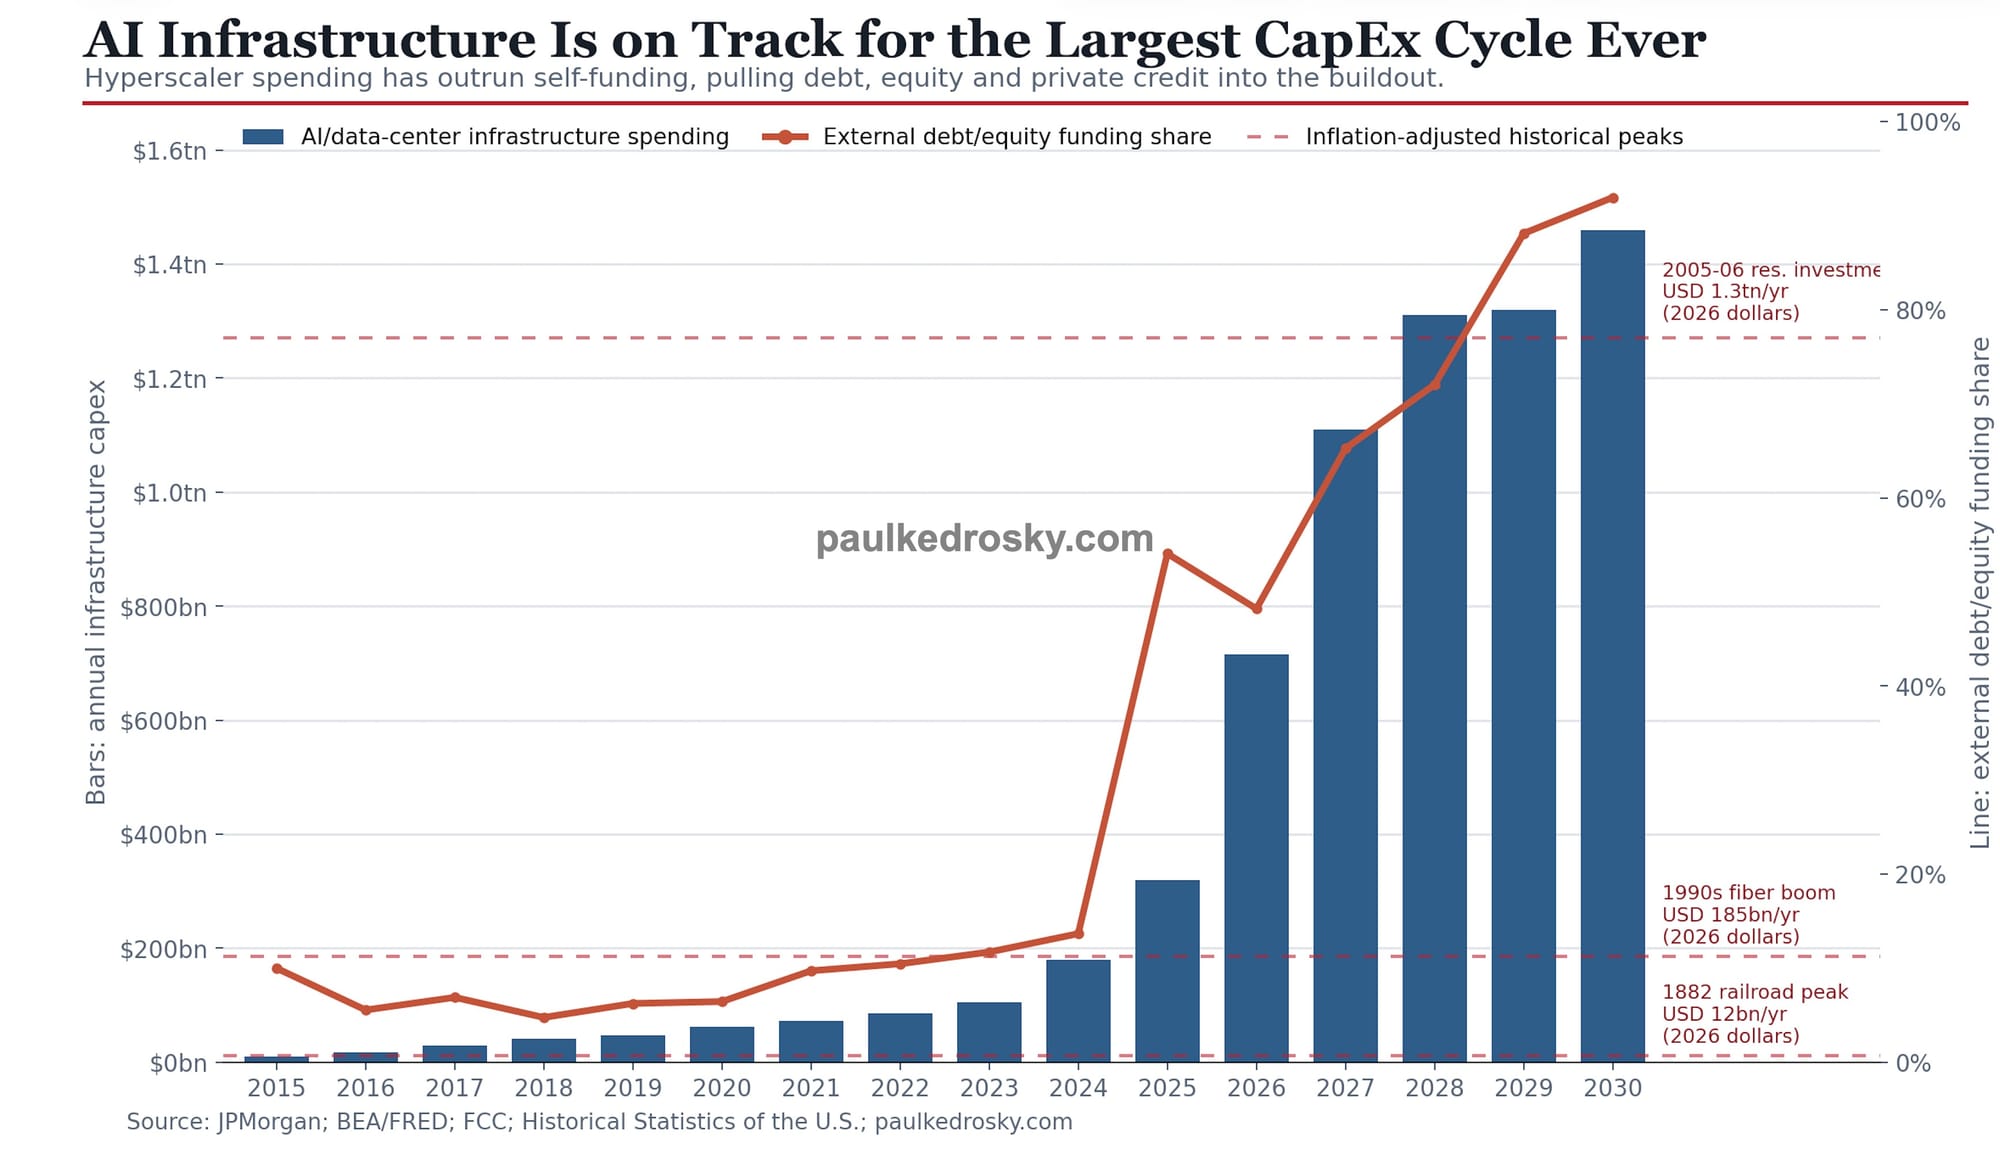
Some implications:
- Debt-market dependency is now systemic.
- At these levels of dependency, a credit contraction or spread widening stops the buildout cold.
- The cycle's fate is tied to debt market appetite, not hyperscaler conviction.