

centers'
- AI data centers' share of GDP (not just GDP growth) is now material.
- A new report buries the lede with respect to how the inference transition is already affecting Nvidia.
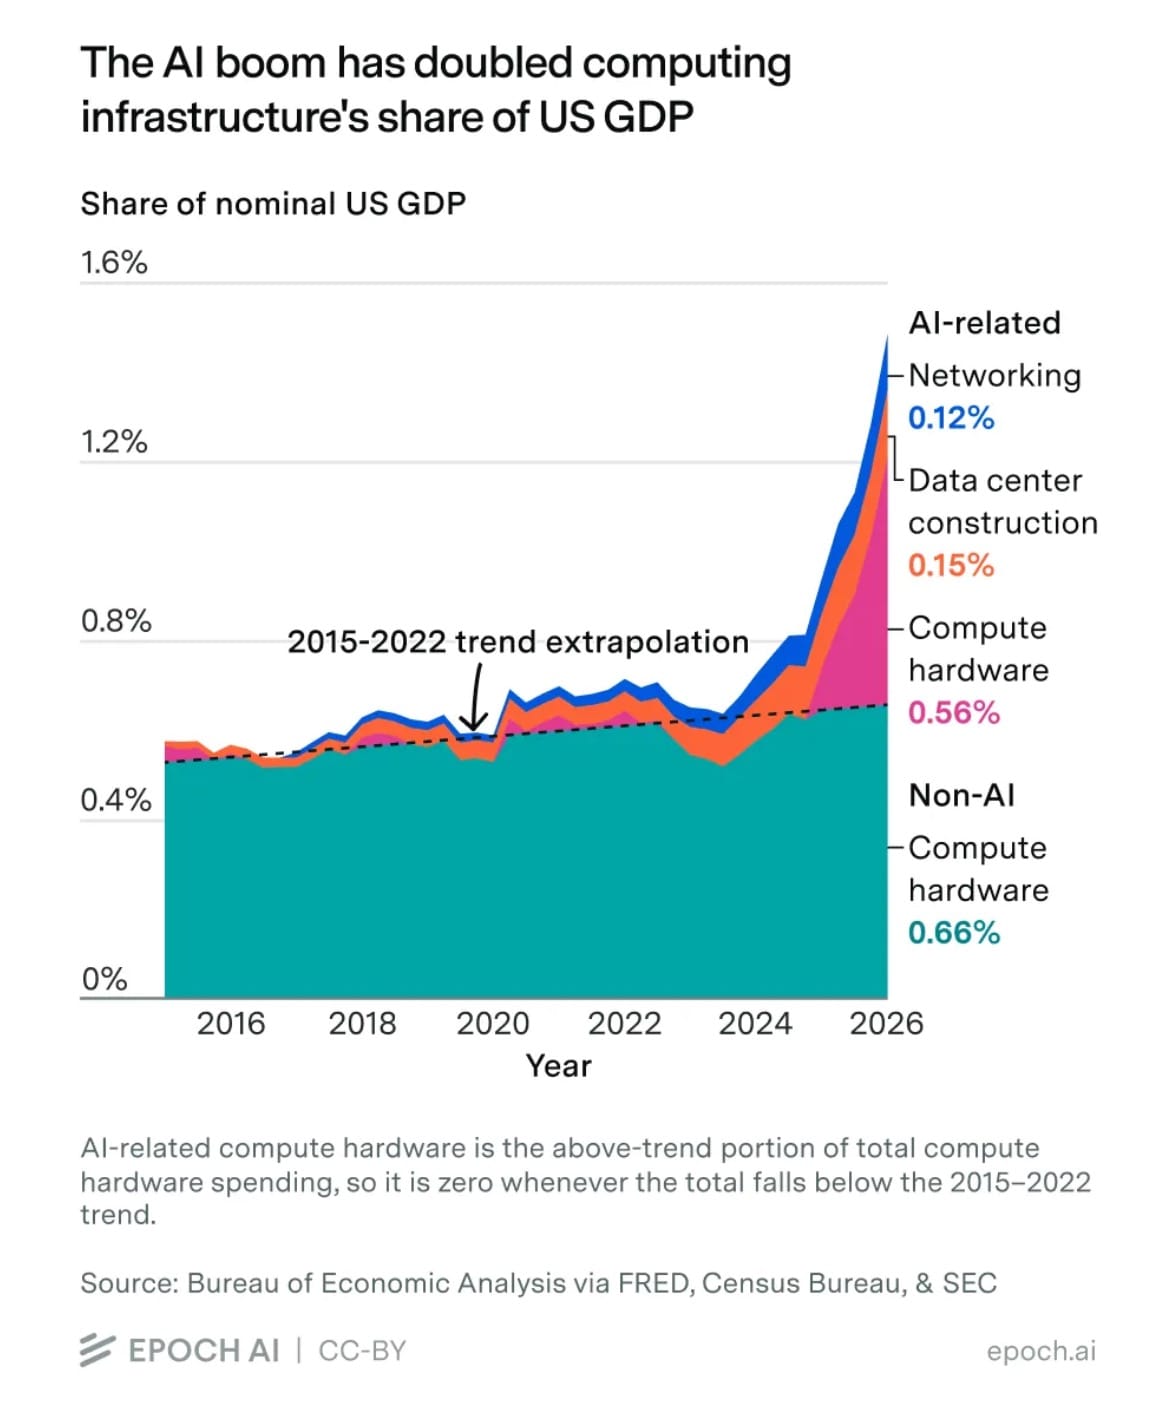
I have written here many times (see here. here, here, etc.) about the sharply growing role of AI capex in US GDP growth, but it is now becoming material in GDP outright. As the following Epoch figure shows, the ongoing AI infrastructure buildout has compressed a decade of capital spending into about two years. Computing infrastructure's share of nominal US GDP sat near 0.5% for most of the 2015–2022 period, with a gentle upward trend. Then it broke sharply upward around 2023, nearly tripling to approach 1.6% of GDP by 2026. This was driven almost entirely by AI-related compute hardware, data center construction, and networking layered on a non-AI compute data center base that never moved.
Some implications:
- The AI capex surge is genuinely anomalous, not a trend extension.
- The 2015–2022 baseline was slow and stable. What's happening now is a structural discontinuity.
- Non-AI compute hardware (~0.66% of GDP) has barely budged.
- The entire increment is AI-specific.
- The buildout is not a broad-based tech investment. but a narrow, concentrated bet by a small number of hyperscalers.
- This concentrates both the upside and the systemic risk.