


Here are recent rough notes from the site.
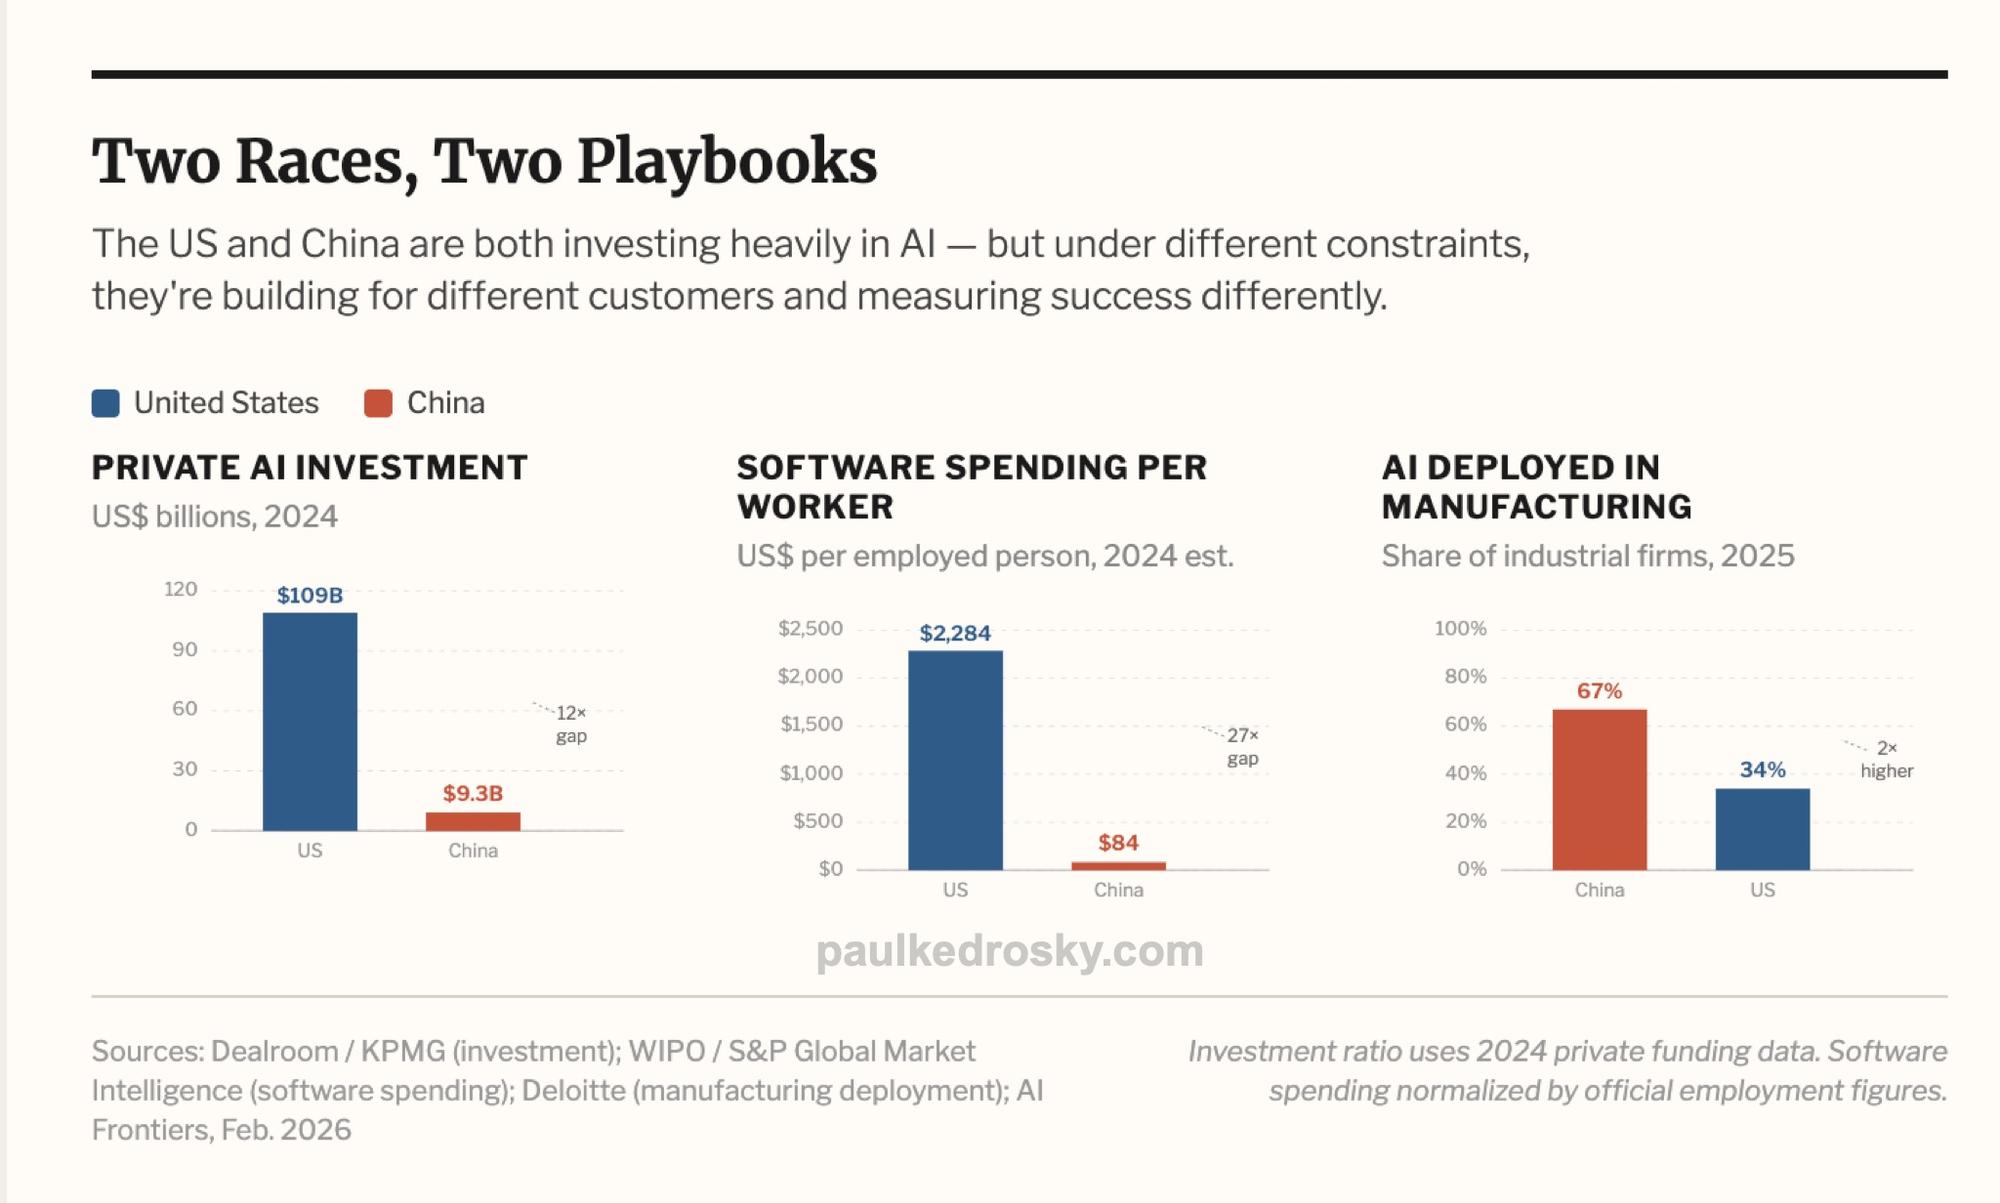
Striking differences wrt how China and US are spending on AI and deplaying it. Chna isn't spending nearly as heavily on frontier platforms, or on software for white collar workers, but is moving quickly to put tools into production in manufacturing, unlike the US.
https://aifrontiersmedia.substack.com/p/china-and-the-us-are-running-different
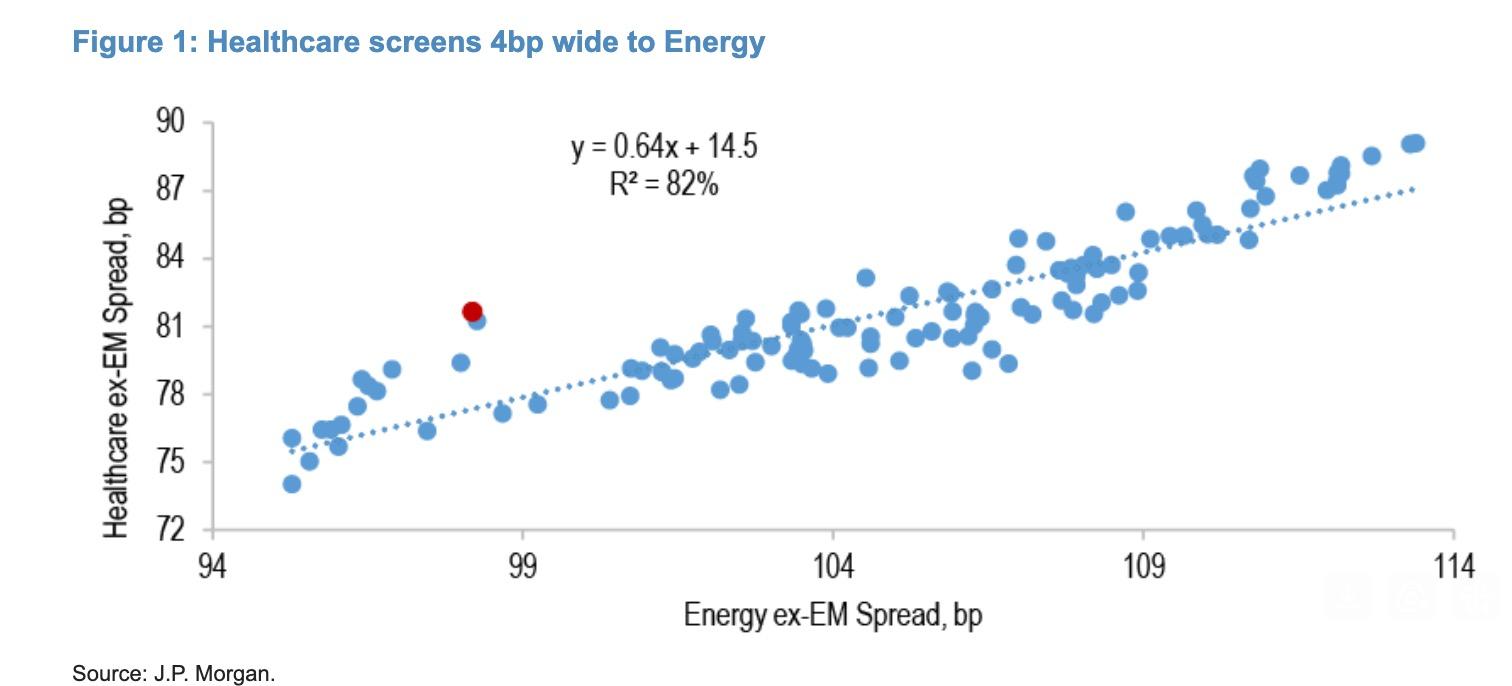
Debt markets are complex and connected systems, so money that flows into tech capex must come from somewhere, and that has consequences. JPM points out today that healthcare credit spread are widening over energy (shorter duration), in part, they argue, because healthcare credit is a source of funds for AI data centers, given similar durations.
Puzzling trends in non-residential specialized trades job growth over last twelve month, as FT Unhedged points out today. Despite data center center construction a growing factor in such trades, job growth decined in first half o flast year, only to acelerate sharply in second half. I'm guessing this was a denominator effect making what's happening, but it is notable.

Compass got a Aaa rating from Moody’s recently for $500m of its latest ABS. The full Moody's justification relies heavily on three high credit tenants making up 96% (!) of the ABS income. This, of course, is a wildly fragile structure given the inherent correlation. Important moment in data center financing, given this will become a template..
https://www.moodys.com/research/Moodys-Ratings-assigns-provisional-ratings-to-a-hyperscale-data-center-Rating-Action--PR_519083